Every autumn, a single number quietly decides how much money tens of millions of older people will live on for the next twelve months. It rarely makes headlines, yet it lands directly in bank accounts from Ohio to Cebu once January begins.
That number is the annual cost-of-living adjustment, better known as the COLA, and it applies to Social Security retirement and disability benefits. It is announced in October, which means the figure that will shape every monthly payment in the coming year is being settled right now.
A raise most retirees never see coming
The mechanism is simpler than its reputation suggests. The adjustment follows a consumer price index that tracks what working households pay for food, fuel, rent and everyday goods. Prices in July, August and September are compared with the same three months a year earlier, and the percentage difference becomes the raise.
If prices barely moved, the bump is small. If inflation ran hot, retirees get more. And when prices fall, benefits are not cut: the adjustment simply stays at zero.
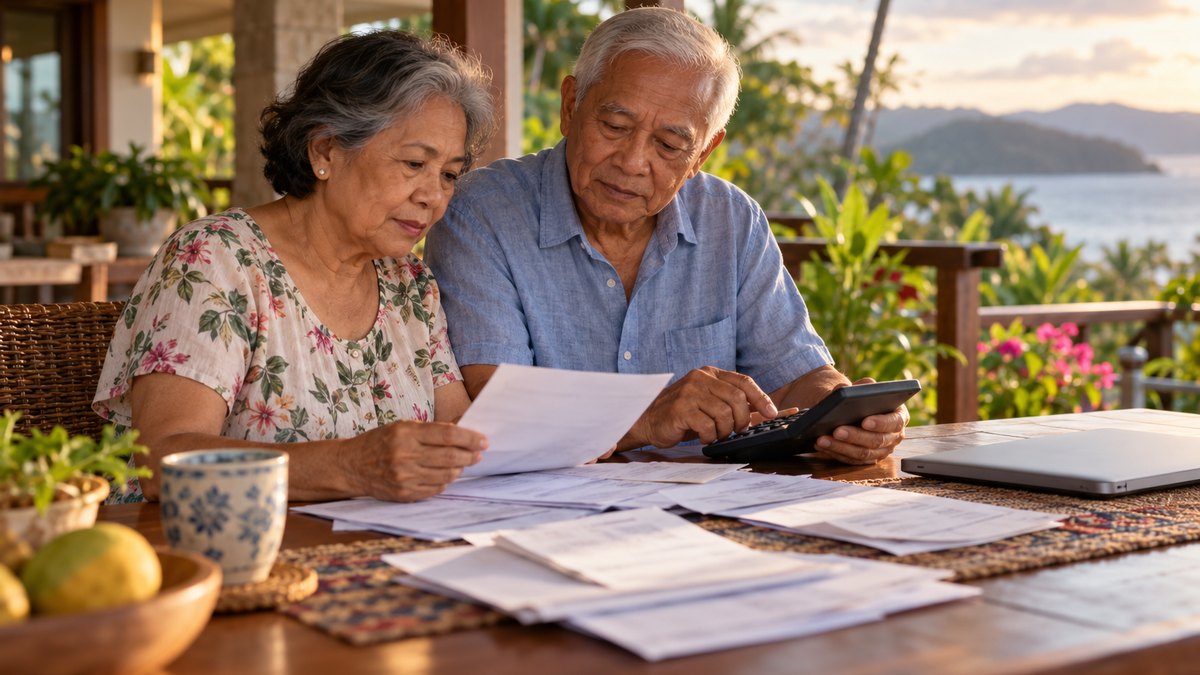
“People think somebody in Washington votes on it every year,” says Linda, a 71-year-old retired school secretary who now splits her time between Arizona and her late husband’s hometown near Iloilo. “I only learned recently that it’s basically automatic. It’s math, not politics.”
Why the January deposit can still look smaller
Here is the part that catches many people off guard. The COLA is applied to the gross benefit, but what reaches the bank is the net amount after deductions. For most retirees enrolled in Medicare, the Part B premium is taken out before the money arrives.
That premium is reset every year as well. In some years, a large share of the raise is swallowed by a higher premium, leaving retirees with an increase of only a few dollars. A modest COLA paired with a steep premium jump can make January feel like a pay cut.
The letter that reveals your exact amount
The national percentage is only half the story. Each beneficiary receives a personal notice showing the new monthly figure, the deductions and the final deposit. Those notices go out in December, and people with an online account can usually read theirs in the message center a little earlier.
Financial planners say this is the document worth opening carefully rather than tossing into a drawer. It is where you can spot:
- the new gross benefit after the cost-of-living increase;
- the updated Medicare premium deducted each month;
- any change in voluntary tax withholding;
- the exact amount that will land in your account in January.
“I used to throw it in a drawer,” Linda admits. “Now I sit down with a cup of coffee and compare it line by line with last year’s. Twice I found something worth calling about.”
What it means for retirees living abroad
The adjustment does not stop at the border. Americans who retired overseas, along with many Filipino-Americans who came home after decades of work in the States, receive the same percentage increase as beneficiaries living in Florida or California.
For them, the real value of the raise also depends on the dollar-to-peso exchange rate. A generous COLA can be partly erased if the peso strengthens, while a weaker peso can make a small raise go further at the market in Manila or Davao.
Retirees overseas also face timing quirks. International deposits can arrive a few days later than domestic ones, and some still receive their benefits through banks that convert currency at unfavorable rates. Reviewing those fees once a year can protect a meaningful chunk of the increase.
Planning before the new year
The weeks between the October announcement and the first January payment are the ideal window to adjust a household budget. Utility bills, insurance renewals and medication costs often rise at the start of the year too, so knowing the new deposit in advance avoids unpleasant surprises.
A simple routine works for most households: note the announced percentage, wait for the personal notice, then rebuild the monthly budget around the net figure rather than the headline raise.
For Linda, the ritual has become almost comforting. “It’s the one time of year I feel like I actually understand my own money,” she says. “And at my age, that peace of mind is worth more than the raise itself.”